If you’ve got a windfall to invest — a bonus, maturity payout, or savings you’ve finally decided to put to work — the SIP vs lump sum question is usually the first decision you’ll wrestle with. Do you drip the money into a mutual fund every month through a Systematic Investment Plan, or do you invest the whole amount in one shot and let it ride? The honest answer is that neither option is universally “better” — it depends on what the market is doing, how long you plan to stay invested, and how much volatility you can stomach. Here’s how to actually think about the trade-off, with numbers you can check against the SIP Calculator.
What SIP and Lump Sum Actually Mean
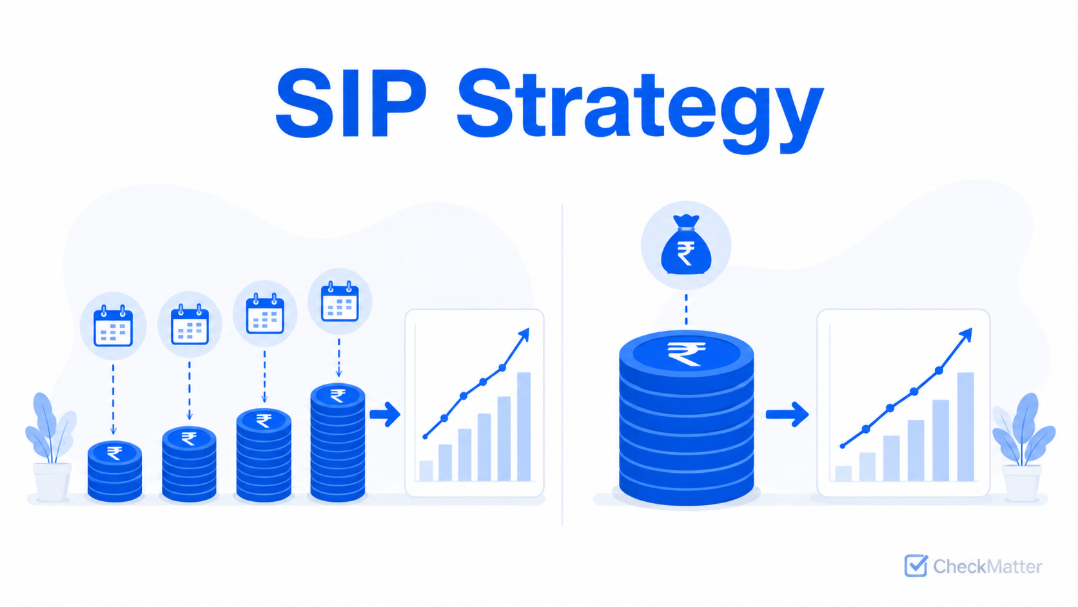
A Systematic Investment Plan (SIP) lets you invest a fixed amount at regular intervals — usually monthly — into a mutual fund scheme, instead of committing everything at once. A lump sum investment, by contrast, puts your entire amount into the market on a single date. Both routes can go into the exact same fund; the only difference is the timing and pacing of your entry.
SIP vs Lump Sum: How Rupee Cost Averaging Changes the Math
The core argument for SIP is something called rupee cost averaging. Because you’re investing a fixed amount every month regardless of the fund’s Net Asset Value (NAV), you automatically buy more units when prices are low and fewer units when prices are high. Over time, this smooths out your average purchase cost, so you’re not betting everything on the price at one single moment. It won’t guarantee a profit or protect you from a falling market, but it does reduce the damage of investing right before a downturn.
A lump sum investment has no such cushion. Your entire return depends on where the market was on the day you invested. If you happen to invest right before a rally, a lump sum will usually outperform an SIP into the same fund — you got more units working for you, sooner. If you invest right before a correction, the opposite is true.
When Lump Sum Investing Tends to Win
Historically, markets trend upward more often than they fall, which is why lump sum investing statistically outperforms SIP over long horizons in a rising market — every rupee gets more time to compound. If you’re investing in a fund with a long runway (10+ years), already have the cash on hand, and don’t need to time an entry point, a lump sum can be the more efficient choice purely on the math. The catch is psychological: watching a large lump sum dip in value right after you invest is far harder to sit through than watching a smaller monthly SIP installment do the same.
A Simple Example: ₹6 Lakh, Two Ways
Say you have ₹6,00,000 to invest in an equity mutual fund. Route A: invest it all today as a lump sum. Route B: spread it as a SIP of ₹50,000 a month for 12 months. If the market rises steadily over that year, Route A generally ends up ahead because all your money was invested — and compounding — from day one. If the market is choppy or drops in the first half of the year before recovering, Route B often ends up ahead, because your later installments bought units at lower prices. Neither outcome is guaranteed; it’s purely a function of what the market actually does during your entry window, which is unknowable in advance. This unpredictability is exactly why the SIP vs lump sum debate doesn’t have a single right answer — only a right answer for your specific situation and risk appetite.
So Which Should You Choose?
A practical middle path many investors use: if you have a large lump sum but are nervous about market timing, split the difference — invest a portion immediately and stagger the rest through a SIP over 6-12 months. This captures some of the upside of early investment while still averaging into part of the position. If you’re investing money you earn regularly (like a salary), a SIP is the natural choice regardless of the debate, since you don’t have a lump sum sitting around to begin with. Run both scenarios through the SIP Calculator using your actual numbers and expected return assumptions before deciding — seeing the projected outcome side by side makes the SIP vs lump sum choice much less abstract.
Key Takeaways
- SIP smooths out purchase price through rupee cost averaging; lump sum concentrates your entry into a single point in time.
- In a steadily rising market, lump sum investing tends to produce higher returns because more money compounds for longer.
- In a volatile or declining market, SIP tends to reduce downside by averaging your entry price over time.
- Rupee cost averaging does not guarantee profit or protect against losses in a declining market.
- A hybrid approach — invest part as a lump sum, stagger the rest as a SIP — is a common way to balance the two.
FAQ
Is SIP always safer than lump sum?
Not necessarily “safer” in every sense — SIP reduces timing risk by spreading your entry, but your money is still exposed to full market risk once invested, just like a lump sum.
Can I switch from a lump sum plan to a SIP mid-way?
Yes. Many investors split a large amount, investing part immediately and directing the rest into a separate SIP, which effectively blends both strategies.
Does the SIP vs lump sum decision matter for short-term investing?
It matters less for very short horizons (under a year), where market movement in either direction can dominate the outcome regardless of strategy. SIP’s averaging benefit is most meaningful over multi-year horizons.
For more background on how rupee cost averaging and SIPs work, see AMFI’s Investor Corner. Explore more calculators in the CheckMatter tools library, or browse the blog for more finance guides.
What happens if the market falls after you invest?
A lump sum invested immediately before a decline feels the full fall, but it also participates fully if the market recovers. A SIP spreads entry dates across the decline, so later instalments buy more units at lower prices. The outcome depends on the path of the market: a quick fall and recovery can favour money invested earlier, while a long or uneven decline can make staggered purchases more helpful.
If you already invest monthly for a long-term goal, stopping only because prices have fallen removes the instalments that would have bought at lower prices. If you hold a large amount and are uncomfortable choosing one entry date, compare three cases in the SIP Calculator: invest now, spread the amount over 6–12 months, and combine an initial lump sum with a smaller SIP. These are scenarios, not forecasts; mutual-fund returns are not guaranteed.
SIP vs lump sum: the same ₹60,000 through two market paths
The timing result changes with the path of NAV, not just the final return. The following original illustration compares a ₹60,000 lump sum invested in month 1 with six SIP instalments of ₹10,000. It ignores tax, exit load and transaction costs so the timing effect is visible.
| Illustrative six-month NAV path | Lump sum value at month 6 | SIP value at month 6 | What drove the difference |
|---|---|---|---|
| 100 → 85 → 75 → 80 → 90 → 105 | ₹63,000 | ₹71,645 | The SIP bought more units during the decline before recovery. |
| 100 → 105 → 110 → 115 → 120 → 125 | ₹75,000 | ₹67,055 | The lump sum put all the money to work before the steady rise. |
Calculation check: lump-sum units are ₹60,000 ÷ first-month NAV. SIP units are the sum of ₹10,000 ÷ each month’s NAV; total units are then multiplied by the final NAV. These are hypothetical paths, not forecasts.
Decision table: which approach fits the situation?
| Your situation | Approach to examine | Main trade-off |
|---|---|---|
| Income arrives monthly | SIP | Matches cash flow and reduces the pressure to choose one entry date. |
| A windfall is already available | Lump sum or a staged plan | Immediate exposure offers more time in the market but greater entry-date risk. |
| A near-term goal cannot tolerate a large fall | Reassess asset allocation first | SIP timing does not make a high-risk fund suitable for a short horizon. |
| You may stop after a market decline | Automate a sustainable SIP | Behaviour and continuity may matter more than the theoretical winner. |
SEBI’s investor material explains rupee-cost averaging—fixed instalments buy more units when prices are lower and fewer when they are higher—but it does not guarantee profit or protect against loss. Review the SEBI Financial Education Booklet, then use the SIP Calculator to test your own contribution, horizon and assumed return.
Educational illustration only; it is not personalised investment advice. Mutual-fund returns are market-linked.